 ES
 EN
 FR
 JA
 KO
 PT
 ZH
 AR
 FA
 RU
 NL
 MS
 VI
 PH
 TH
 ID


USD – October’s US CPI rates to be the next test for the greenback
The USD seems about to end the week in the reds relenting last week’s gains, yet as these lines are written, October’s US employmetn report is still to be released and could alter its direction. The main issue for the greenback in the past week were the US midterm elections which resulted in a blue wave flipping both the House of Representatives and the Senate. The USD showed little sensitivity but chip shares sunk under the suspicion that Democrats could impose strict regulation for the AI sector.
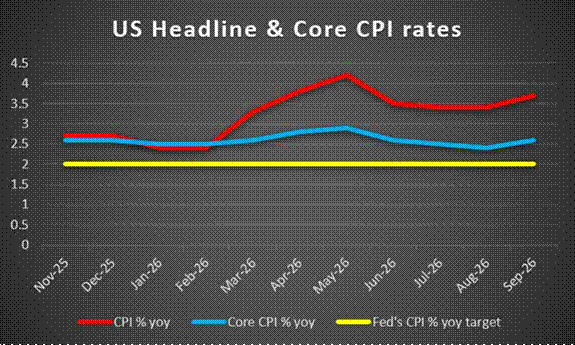
Meanwhile market expectations for the Fed to hike rates eased yet in the coming week, we highlight the release of October’s CPI rates. The rates have been above the Fed target of 2% for some time nbow and a possible acceleration could force the market to readopt more hawkish expectations for the Fed’s intentions and thus provide some support for the greenback and thus we may see US equities and gold’s price slipping.
GBP – Q3 GDP rates eyed
The GBP seems to be about to close the week in the greens against the USD and JPY, and stabilising against the EUR. The main event in the past few days for the pound was BoE’s interest rate decision. The bank as was widely expected hiked rates by 25 basis points (bp) and seemed to be leaning on the hawkish side. Its characteristic that all voted to raise interest rates with one monetary polcy committee member even favourig a double rate hike. The bank also expects the CPI rate to accelerate further, reaching 5.0% by the midst of the coming year, which verifies the hawkish predisposition, yet at the same time did not committ to any particular path regarding its monetary policy outlook.
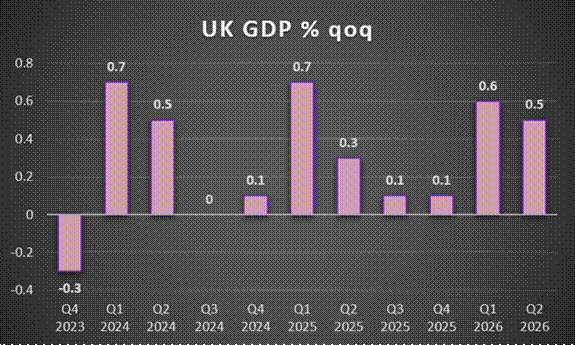
Nevertheless, we still view the decision as being supportive for the GBP and should BoE policymakers sound hawkish in the coming days we may see the pound rising. On a macroeconomic level, coming Thursday, we highlight the release of UK’s preliminary GDP rates for Q3 and a possible acceleration could provide some support for the Sterling. On a deeper fundamental levelm we note that the re- examination of UK’s relationship with the EU is in progress with a big meeting scheduled on the 20. of November. Any indications of closer ties of the UK with the EU may provide support for the GBP and vice versa.
JPY – BoJ’s intentions to move the JPY
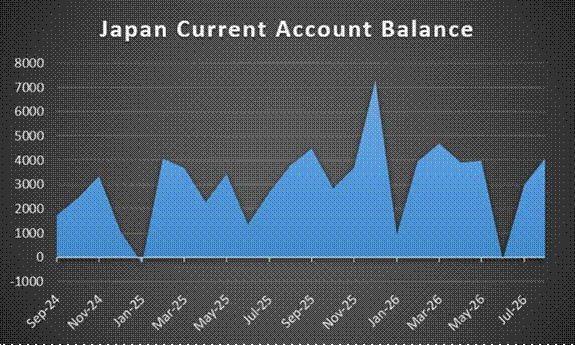
JPY is about to end the week, weaker against the EUR and GBP but not the USD. In the coming week we have some financial releases of interest from Japan on the calendar like the Current account balance for September on Tuesday and October’s PPI rates on Thursday, yet our interest is mostly on BoJ’s monetary policy intentions. On Tuesday we get BoJ’s summary of opinions for the October meeting. Should the document show that BoJ policymakers are increasingly leaning towards a rate hike in the December meeting we may see JPY getting some support.
JPY OIS marginally imply that a rate hike in the December meeting is possible by pricing in such a scenario by 59.7% currently. BoJ Governor Ueda in a speech on Monday has all but locked in a December rate hike, yet we suspect that he is getting some opposition within the Board of the central bank. Hence we intend to pay also close attention to the speech of BoJ Board Member Asada, next Thursday. The BoJ policymaker was one of the three appointed by Japan’s Prime Minister Takaichi and may prefer to sound more dovish, in which case JPY may lose ground.
EUR – Easy going week ahead
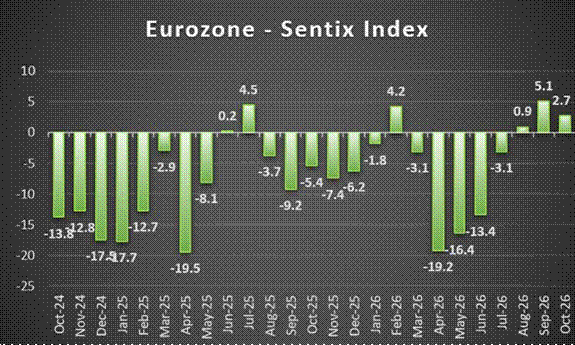
The common currency seems to be gaining against the USD and JPY, but remains relatively stable against the pound for the week. On a fundamental level the political discontent is continued, which tends to provide some uncertainty for Euro Zone’s political outlook and thus weighs on the common currency. On a macroeconomic level, we note the release of the forward looking Sentix index for November, yet intend to focus on the release of Euro Zone’s revised GDP rate for Q3 next Friday.
A possible slow down of the rate could weigh on the single currency given that growth in the area is allready at relatively low levels. On a monetary level, the ECB is expected to hike rates in the December meeting, though the expectations are not that high, nevertheless we take the market’s expectations for the ECB’s intentions as a plus for the EUR. We also note that ECB President Lagarde’s early resignation tends to post some question marks for the bank’s monetary policy tightening, yet that is related to the first half of 2027, not immediately.
AUD – Market sentiment to lead the Aussie
AUD is about to end the week considerably weaker against the USD. On monetary policy level, Aussie traders expect widely the bank to remain on hold in the December meeting, which is understandable given that the bank proceeded with its fifth rate hike for the year on Tuesday.
It should be noted that RBA’s cash rate has now reached its highest level since 2008, yet should inflationary pressures in the US economy prove to be persistent we may see the bank being forced to raise rates again in the coming year. On a macroeconomic level we have no high impact financial releases on the calendar, maybe with some interest being generated by the release of China’s trade data for October on Tuesday, where a possible acceleration of China’s import growth rate could support the Aussie given the wide amount of raw materials delivered to China from Australia.
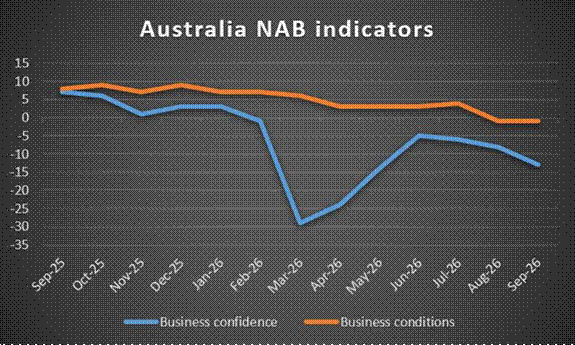
Around the same time we also note the release of Australia’s business conditions and confidence indicators for October. On a deeper fundamental level we also note that the Aussie is particularly sensitive to the market sentiment as it is considered a riskier asset in the FX market. Hence a possibly more cautious market sentiment could weigh on AUD, while a more risk on approach by the markets could support it.
CAD – BoC’s intentions remain key for the Loonie
The Loonie is about to end the week lower against the USD after three consecutive weeks of gaining, yet we note that Canada’s October employment data are still to be released as these lines are written so the direction of CAD may be altered. On a monetary level, given BoC’s interest rate hike last week, the bank is expected to remain on hold in December. Yet the markets’ expectations are marginal for the bank to keep rates steady next month and should inflationary pressures prove to be resilient another rate hike may be necessary. Yet, BoC Governor Macklem did not sound the alarm when he testified before the House of Commons finance committee yesterday.
BoC’s Governor was reported stating that the Canadian economy was in excess supply and that the Canadian Government’s spending was not adding to inflationary pressures. Yet the energy shock remains for the time being and may force BoC to turn more hawkish should it persist. Hence we highlight the release of the bank’s monetary policy deliberations for its last meeting. Should the document show that the bank intends to take a break from monetary policy tightening we may see CAD losing some ground and vice versa a more vigilant, hawkish approach by the bank may provide some support.
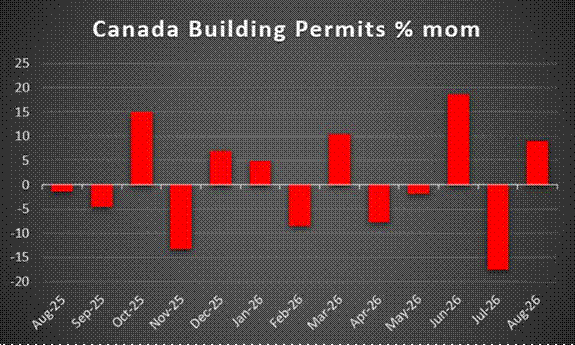
On a macro-economic level calendar is rather empty of high impact financial releases from Canada yet we would like to the release of the building permits, manufacturing sates and wholesale trade growth rates on Thursday and Friday, all for September. A possible acceleration of the rates could provide some support for the Loonie.
EXENCIÓN DE RESPONSABILIDAD: This content is for general informational and educational purposes only and should not be considered investment advice or investment recommendation.


