 VI
 EN
 FR
 ES
 JA
 KO
 PT
 ZH
 AR
 FA
 RU
 NL
 MS
 PH
 TH
 ID

USD – Fed’s intentions in the epicenter of attention
The USD prepares to the week in the reds, after four consecutive weeks of gains. The easing of market expectations for the Fed to hike rates, weighed on the greenback, despite inflationary pressures getting a boost beyond market expectations, both on a consumer as well as on a producers’ level for the past month. Fed policymakers seem to lack the necessary hawkishness and it’s characteristic that Fed Chair Warsh avoided to mention anything about the path of interest rates in today’s Asian session. Given also the low number of high impact financial releases from the US in next week’s calendar, we expect fundamentals to lead the USD in the FX market. Should market expectations for the Fed to tighten its monetary policy be enhanced, we may see the USD getting some support and vice versa a continuing of the easing of the market’s expectations for the Fed to tighten its monetary policy could weigh on the USD.
GBP – Employment and CPI rates to be watched
AUD may have been the winner of the week in the FX market, being in the greens against the USD, the EUR and JPY. UK’s GDP rates for August on a 3M/3M and y/y basis accelerated beyond market expectations brightening the macroeconomic outlook of the UK somewhat. In the coming week we are to focus on inflation and employment given the release of UK’s CPI rates for September and August’s employment data. Should we see the UK employment market tightening in August, we may see the pound getting some support.
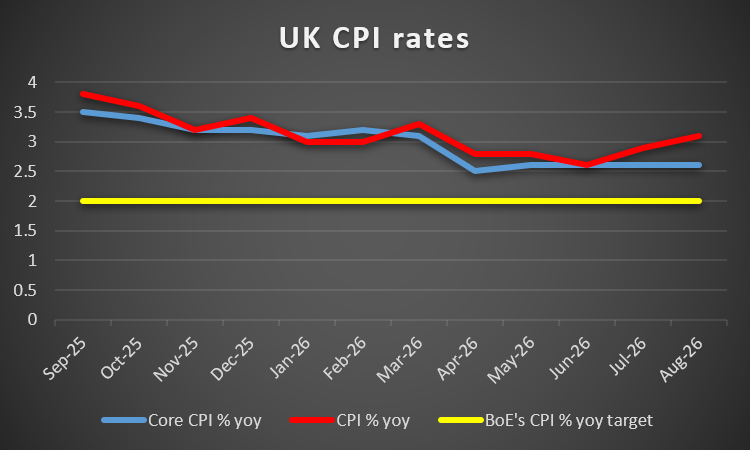
Yet the main issue may be the release of the UK CPI rates for September as an acceleration of the rates could add more pressure on BoE to tighten its monetary policy, thus providing support for the GBP. However we note that BoE Govenror Bailey does not seem to be conviced for the width of inflationary pressures in the UK economy, at least as stated yesterday. We note that the market currently prices in two rate hikes to come by BoE until the end of the year.
JPY – Japan’s September CPI rates could move the Yen
JPY seems to remain relatively stable against the USD for the week, despite the weakening of the latter. In the coming week, on a macroeconomic level, we highlight the release of Japan’s CPI rates for September, next Friday. A possible acceleration of the rates could provide some support for the JPY, as it could enhance the hawkishness of BoJ and thus provide some support for JPY. It’s characteristic how BoJ Governor Ueda on Friday reiterated the risks of underlying inflation overshooting the central bank’s 2% target, as reported by Reuters. For the time the bank is expected to remain on hold in October and proceed with a rate hike in December, which tends to be supportive for the JPY. On a deeper fundamental level, we note that the carry trade effect seems to have been paused which also may be supportive for JPY.
EUR – Preliminary October PMI figures eyed
The common currency seems to be in the greens for the week against the USD and JPY, yet loses ground against the GBP, sending some mixed signals. In the coming week, we highlight the release of October’s preliminary PMI figures of Germany, France and the Euro Zone as a whole. A possible rise of the figures could signal a faster expansion of economic activity across sectors, a major issue for the Euro Zone on a macroeconomic level.
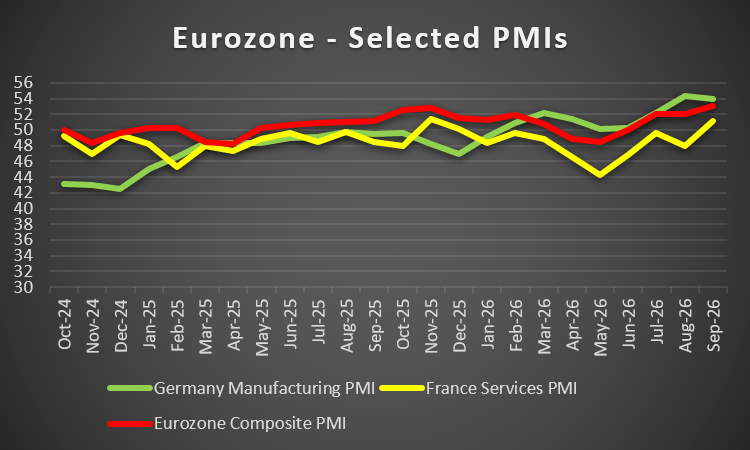
On a monetary level the acceleration of the HICP rates maintains hawkish expectations of the market for ECB’s intentions. We should note that the market currently expects the bank to remain on hold in the coming meeting, end of October and proceed towards a rate hike in December. The Euro Zone seems to be particularly sensitive to the level of energy costs, hence should oil prices remain high or even rise further, we may see inflationary pressures getting a boost, adding more pressure on the ECB to tighten its monetary policy earlier. Also we maintain, on a deeper fundamental level, our worries for the political outlook in the Euro Zone, given the political uncertainty in France, Germany and Spain, which could weigh on EUR.
AUD – Fundamentals to lead the Aussie
Surprisingly the Aussie was unable to benefit from the weakening of the USD during the week. The release of Australia’s employment data for took AUD traders by surprise as the employment figure dropped deep into the negatives reaching -39.3k and the unemployment rate ticked up to 4.7%. The data weighed on the Aussie as the advised caution to the RBA in tightening its monetary policy. For the time being the bank is expected to remain on hold until the end of the year, which may be somewhat bearish for the Aussie. On a deeper fundamental level, we note that the Aussie as a commodity currency, tends to be sensitive to the market’s risk on/off tendencies. Should the market’s sentiment improve, we may see AUD getting some support and vice versa should the market sentiment turn more cautious, AUD may lose ground.
CAD – September’s CPI rates to shake the Loonie
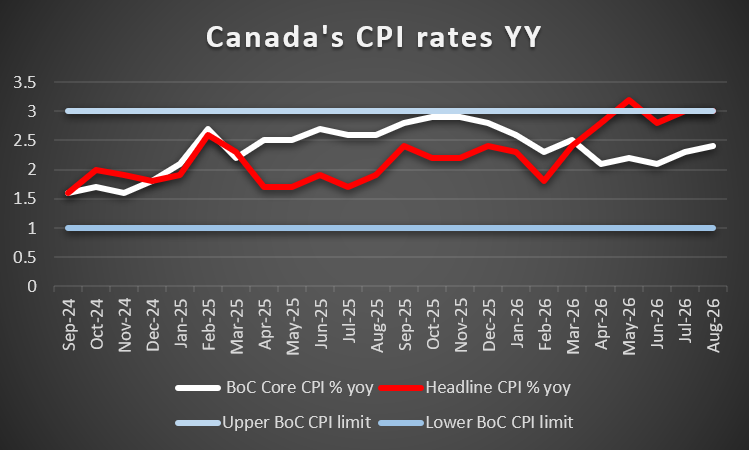
The Loonie was able to reverse a five week losing streak against the USD. In the coming week we expect Loonie traders to focus on the release of Canada’s CPI rates for September.
A possible acceleration of the rates could provide some support for the CAD as it could enhance the pressure on BoC to tighten its monetary policy. For the time being the bank is expected to remain on hold and CAD OIS imply a probability of 69.7% for such a scenario to materialise, with the rest implying that a rate hike is also possible. It should be noted that BoC Governor Macklem noted that BoC has not yet hiked rates, yet prolonged high energy prices make such a stance harder to keep.
On a fundamental level, we note that the US-Canadian trade war is ongoing, with tariffs in place and without any easing on the horizon. The US-Canadian trade war, tends to provide bearish tendencies for the Loonie, albeit we have to note the efforts of the Canadian government to transform the country.
DISCLAIMER: This content is for general informational and educational purposes only and should not be considered investment advice or investment recommendation.


