 VI
 EN
 FR
 ES
 JA
 KO
 PT
 ZH
 AR
 FA
 RU
 NL
 MS
 PH
 TH
 ID


USD – Fed’s minutes to be released
The USD is about to end the week in the greens in the FX market. In the coming week we expect fundamentals to lead the greenback given the lower number of high impact financial releases on the calendar.
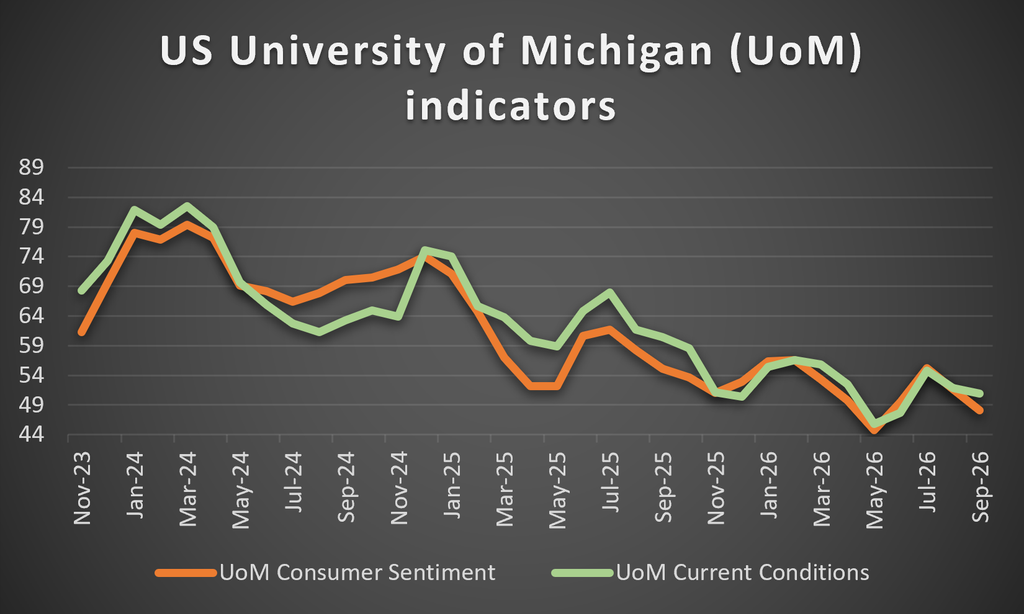
The release of the Fed’s September meeting minutes on Wednesday is tends to dominate given also the weight of the market’s, currently hawkish, expectations bear. The document is to shed more light on the balance of power within the bank and should we see an increased number of Fed policymakers favouring a faster tightening of the bank’s monetary policy we may see the USD getting some support, while gold’s price and US equities may slip.
Also we note that US yields tend to remain high and should they remain at such elevated levels, or even rise further, we may see the greenback being supported, while they may weigh on gold’s price and US equities, which showed substantial resilience until now.
GBP – Turning toward the EU
Also GBP could be led by fundamentals in the coming week given the relative empty calendar from UK high impact financial releases. On a monetary level the market’s expectations for BoE continue to be leaning on the hawkish side, given the current expectations for the bank to hike rates in its November meeting.
Such expectations may lend some support to the pound in the coming week should they be maintained or intensify.
On a political level we maintain some worries for UK PM Andy Burnham’s intentions. It’s characteristic that the UK PM open widely the door to the UK possibly rejoining the EU. On a political level UK PM Burnham’s intentions are far wider as in hid Labour Party Conference speech, pledged to give the UK “a new social contract” including social housing, better education and more affordable care for elderly.
Overall, should UK PM Burnham actually try to start delivering on his promises, we may see a wider shift to the left of the UK fiscal priorities, which in turn may create uncertainty for pound traders and weigh on the pound.
JPY – BoJ’s intentions remain key
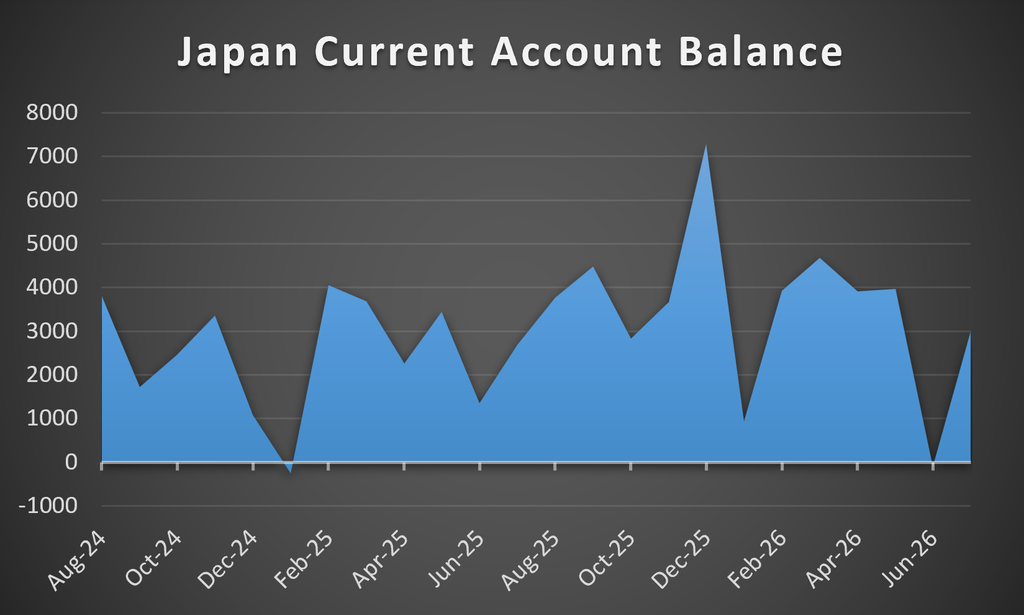
JPY seems about to end the week with some modest losses, yet still in the reds against the USD, for a third week in a row. No major financial releases are on JPY traders’ calendar, maybe with the exception of current account balance and the overtime and cash earnings pay rates for August.
Hence we turn our attention once again towards deeper fundamentals. Ona monetary policy level, BoJ seems determined, with the exception of two policymakers, to maintain a restrictive, hawkish approach. The substantial beyond-expectations acceleration of Tokyo’s CPI rates for September tends to add more pressure on the bank to tighten its monetary policy.
Hence should we see any BoJ policymaker actually signalling a more hawkish approach we may see JPY getting some much needed approach. Yet the bank seems to be facing political pressure to ease its rate hiking path, which tends to intensify doubts for possibly faster rate hikes and weighs on the JPY.
We also note that the continuous weakening of JPY, tends to increase the possibility of a market intervention by BoJ to JPY’s rescue.
EUR – EUR about to end the week deep in the reds
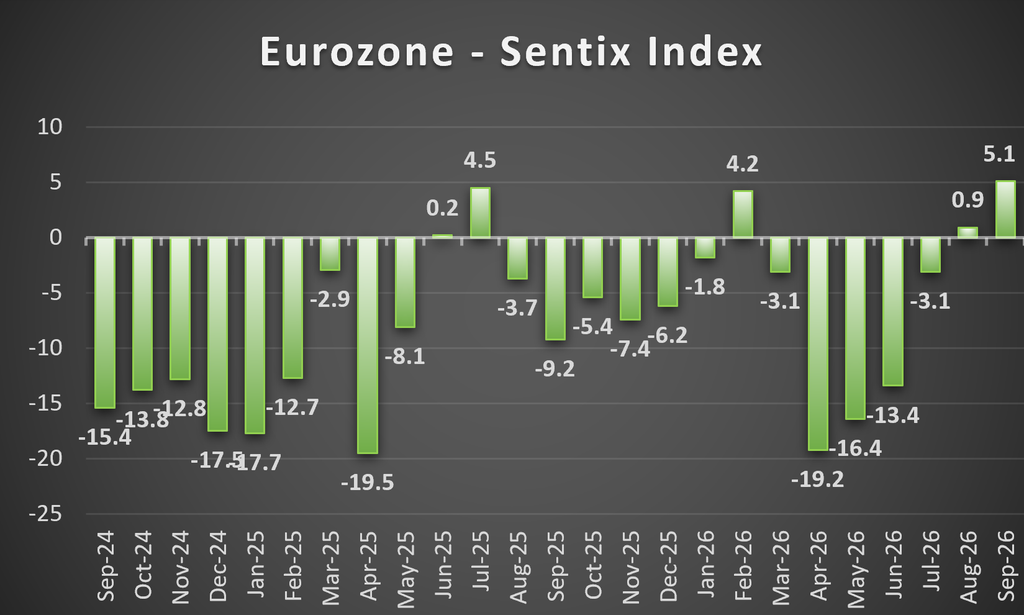
We mentioned that the common currency may be in a tight spot, yet it seems ready to end another week, deep in the reds against the USD, with the losses reaching 3.5% for the past four weeks.
On a macroeconomic level, there are some financial releases of interest, but nothing ground shaking for EUR traders. On a monetary level, the ECB is expected to remain on hold in the October meeting and hike rates again in December.
Yet the acceleration of the HICP rate for the Euro Zone, reaching 3.8%yy is ringing the alarm bells for the ECB to act faster. Currently the interest rate differentials of the US and the Euro Zone seem to remain stable, yet wide to the Fed’s favour. Hence we could see ECB policymakers maintaining a hawkish tone, which in turn may boost the EUR somewhat.
On a fiscal level, we note that French and Italian bonds have come under pressure and the spread with German Bunds seems to be widening. Hence the added pressure on Southern economies of the Euro Zone could weigh on the common currency.
Also we note the possibility of political uncertainty in France given that the election campaigns for the next Presidential election is about to begin. Please note that Marine Lepen’s right wing populist National Rally (NR) surged in Sunday’s Senate elections, which underscores the possibility of NR winning also the presidential elections.
Political dissatisfaction in Europe is evident in many large democracies of the Zone, including Germany and France, and tend to create political uncertainty, which could weigh on the single currency.
AUD – Market sentiment to lead the Aussie
As expected also the Aussie was victimised by a stronger USD in the FX market. On a macro-economic level, the acceleration of the CPI rate, failed to provide substantial support to AUD, yet still adds more pressure on RBA to continue tightening its monetary policy.
Please note that RBA delivered a 25 basis points rate hike as was expected. Yet the release weighed on AUD, as the bank’s forward guidance tended to disappoint Aussie traders, despite actually sounding hawkish.
The market currently expects the bank to hike rates again in November and then hold for the year, which could be somewhat supportive for AUD.
On a deeper fundamental level, we note that the market sentiment is critical for AUD given the market’s perception of a riskier nature as it is a considered a commodity currency. A possible improvement of the market sentiment could push the Aussie higher, while a more cautious approach could weigh on AUD.
CAD – September’s employment data in focus
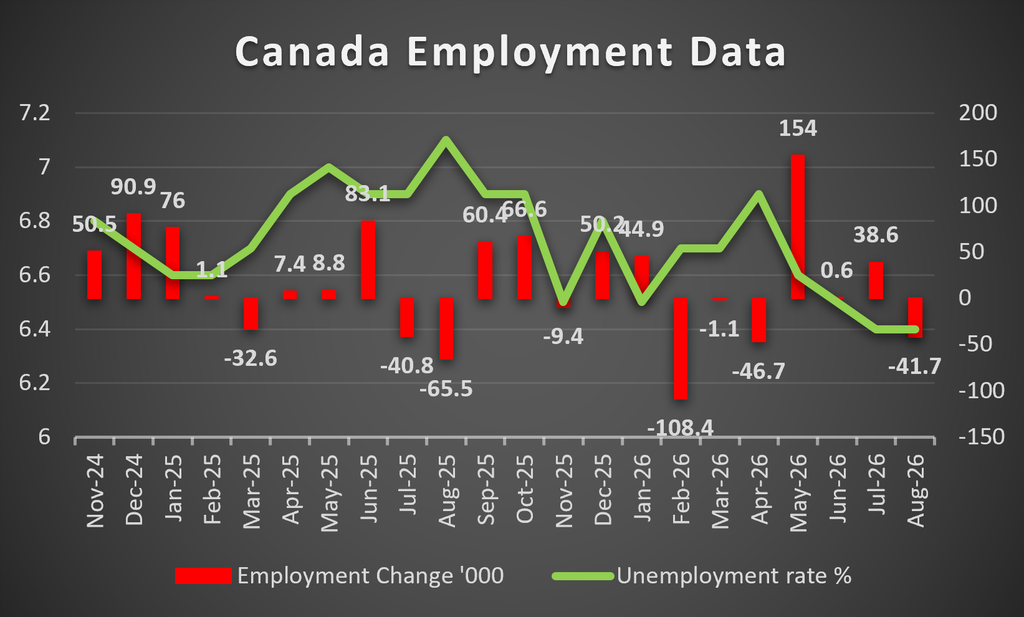
The Loonie seems to be resisting the strengthening of the USD for the week. In the coming week, we highlight the release of Canada’s employment data for September next Friday.
A possibly easing Canadian employment market could weigh on the Loonie, while a more than expected tightening could provide some much needed support for the CAD as it could intensify market expectations for the BoC to tighten its monetary policy.
The bank is currently expected to keep rates unchanged in its October meeting and deliver a rate hike in the December meeting. A possibly tighter than expected Canadian employment market for September could tilt the scale in favour of a rate hike in the market’s perception.
On a fundamental level, the tensions in the US-Canadian trade relationships are ongoing and weighing on the Loonie. In a latest development the US ban on Canadian dairy and alcohol came into effect escalating the tensions.
At the same time US officials tend to point to an impasse in the negotiations between the two parts. Any further escalation of the tensions in the US-Canadian trade relationships could weigh further on the Loonie.
Disclaimer:
This information is not considered as investment advice or an investment recommendation, but instead a marketing communication.

